Network League Table Wealth - Q3 2026
For more information on networks click Network Directory below
Click league table to view full size.
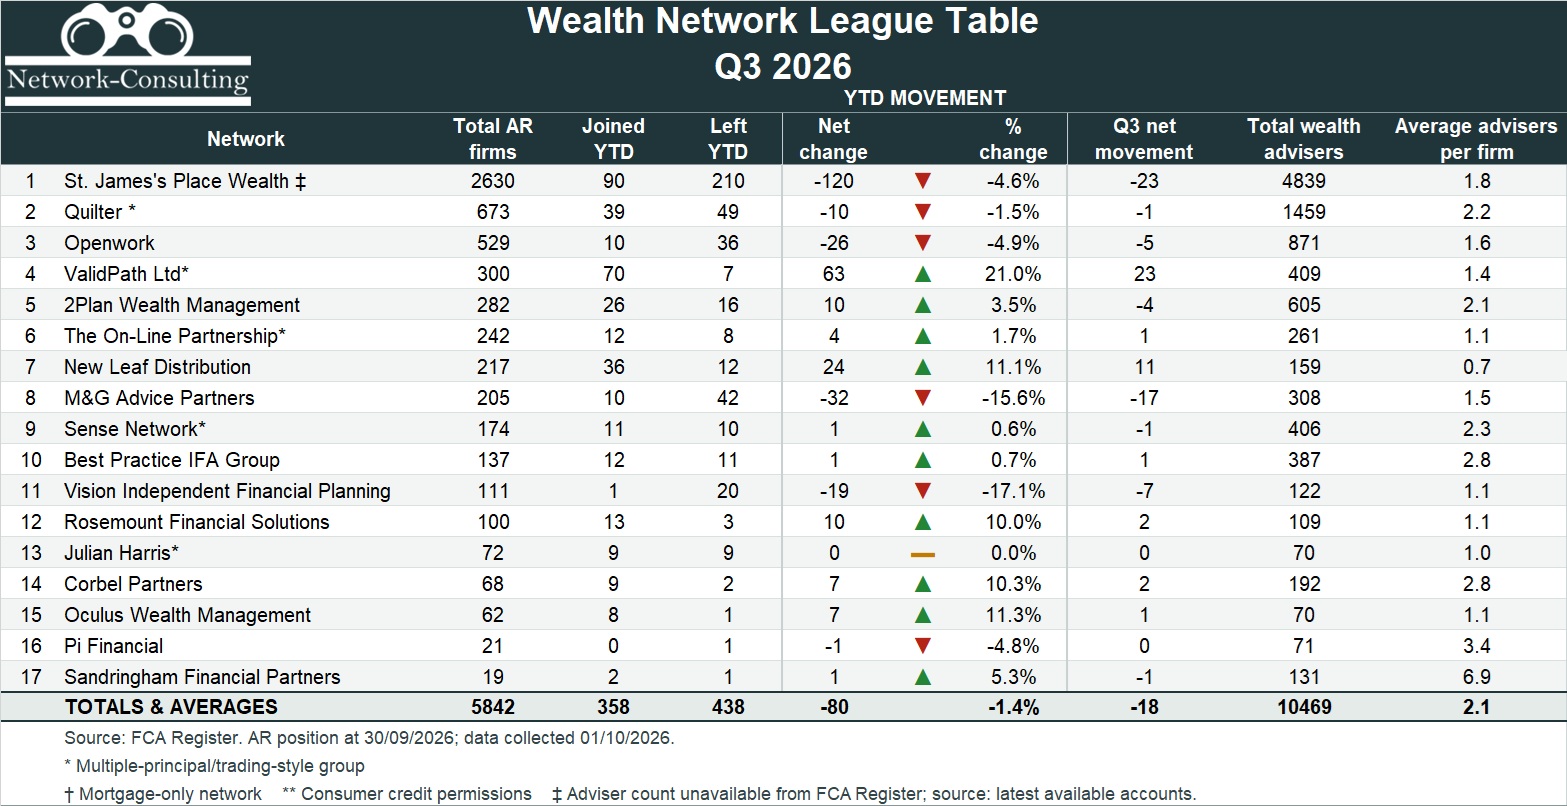
The data source for the table below is the FCA register and was correct at 2nd October 2026.
It illustrates the movement of Appointed Representative firms for each network over the period 1st January 2026 to 30th September 2026.
It is prioritised by total number of AR Firms, adviser numbers for this table only include mortgage advisers.
The size of a network does not mean they will be best for you. If you’re looking for a network, please get in touch and let us help find the best one for YOU.
* Denotes networks with multiple networks under one brand.
** Denotes network specialising in consumer credit
† Denotes dedicated mortgage networks.
Wealth advisers includes all retail investment and pension advisers.
For more detail regarding the table and how they are collated, please go to the Network League Table overview
The latest Network Consulting Wealth Network League Table shows a market in which growth is becoming increasingly concentrated, but also one where the headline AR numbers don’t necessarily tell the whole story.
Across the networks included in the table, there are 5,842 appointed representative firms and 10,469 wealth advisers. During 2026 to the end of September, the table records 358 firms joining and 438 leaving, producing an overall net reduction of 80 firms.
Behind those totals, however, there are some significant differences in direction.
ValidPath continues to stand out. The network has grown to 300 AR firms, with 70 joining and just seven leaving during the year – a net increase of 63 firms, equivalent to 21% of its current AR population.
There is wider context to that growth. In June, Rimbal announced that £300m FUM advice firm Manning & Company had joined its ValidPath proposition, with Rimbal also providing capital to support the firm’s longer-term growth plans. Rimbal has subsequently announced senior appointments in both technology and commercial roles as it continues to invest in the proposition. Rimbal
At the other end of the table, St. James’s Place remains by some distance the largest organisation, but the FCA data continues to show considerable movement within its AR population. The table records 90 firms joining during the year against 210 leaving, giving a net movement of -120.
Openwork presents an interesting example of why AR numbers shouldn’t necessarily be viewed in isolation. Its network has reduced by a net 26 firms YTD, while 2Plan has grown by 10. At group level, however, Openwork continues to invest in growth, acquisitions and succession. In August, the company announced the appointment of a new Director of Mergers, Acquisitions & Succession and confirmed that its Strategic Investments team, supported by its relationship with Bain Capital, is pursuing further acquisition and succession opportunities. The Openwork Partnership
There is also significant change surrounding Best Practice and Oculus, which both appear separately in the table. Söderberg & Partners announced in July that it is acquiring the wider Benchmark business from Schroders. Benchmark supports around 200 financial advice firms and approximately 1,000 advisers, making this a potentially significant development within the wider wealth network market. Söderberg & Partners
Vision is another network worth watching. Our FCA data records only one firm joining during 2026 against 20 departures, reducing its AR population to 111. This contrasts with Rathbones’ public announcement earlier this year that, following a strategic review, it had made a fresh commitment to grow Vision and would make further investment in the network under the leadership of Phil Towner. Rathbones
Among the other positive movements, New Leaf recorded net growth of 24 firms, while Rosemount added 10 and Corbel 7. Corbel’s growth also sits against a wider expansion strategy: the company announced earlier this year that it had secured £10m to support a five-year acquisition programme and subsequently reported completing its 18th acquisition. Corbel
Size and momentum are not the same thing
Perhaps the clearest message from this quarter’s table is that size and momentum should not be confused.
Some of the largest established networks are seeing their AR populations contract, while several smaller organisations are growing rapidly. At the same time, acquisitions, investment, succession strategies and changes in ownership mean that movements in AR numbers provide only one measure of what is happening within a network.
For advisers considering where to place their business, growth can be an important indicator – but it shouldn’t be considered in isolation. Proposition, culture, financial strength, service, technology, charging structure, ownership and longer-term strategy can be equally important.
The fastest-growing network isn’t necessarily the right network – just as the largest isn’t necessarily the best.
The Network Consulting league tables are compiled using information available from the FCA Register at the time of data collection. The FCA Register may subsequently be updated, including retrospectively, and figures may therefore differ from those displayed at a later date.